Copper Backwardation Revisited: The Spread, the Cancelled Share and the COMEX Premium
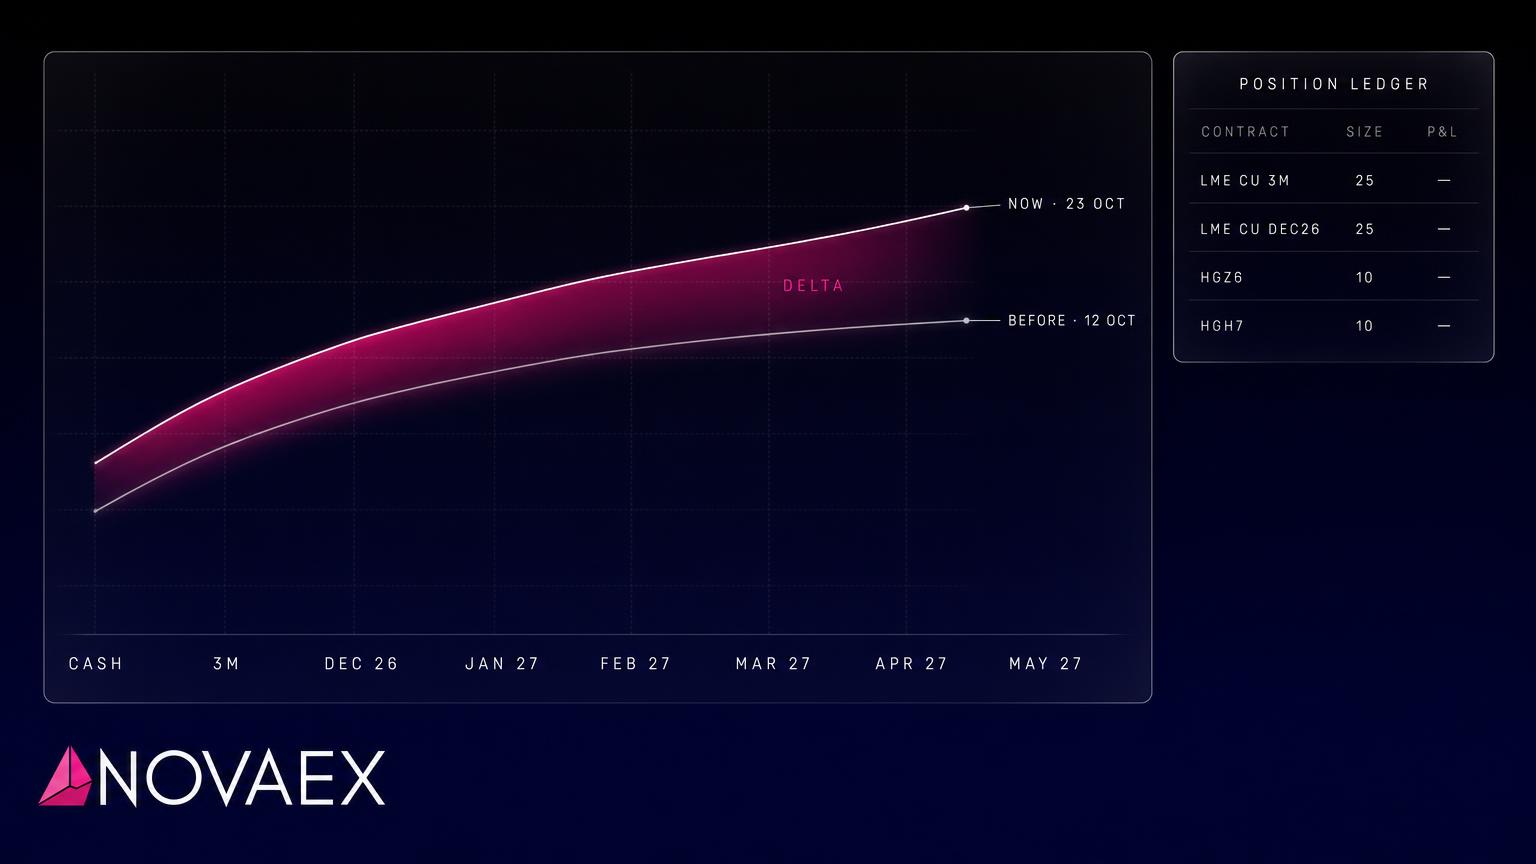
Three threads from our 12 October copper curve piece, re-read against the latest published figures: what moved, and what is still open.
Against our 12 October copper curve piece, the cost of being short prompt metal has fallen, the cancelled share has barely moved and the US pull on metal has faded. The LME cash premium was $64 a tonne on 5 October, down from $248. Three questions stay open: cancelled metal, the COMEX gap and Yangshan.
Every figure below is dated and linked. Check it against today's print before you act on it.
Thread In the 12 October piece Latest published Direction
Cash to three-month $248 a tonne, after a $545 peak $64 a tonne, 5 October Narrower
LME stock and cancelled share 240,250 t, cancelled 50% 244,900 t, 5 October; cancelled reported near half (unconfirmed) Stock slightly higher, share about the same
COMEX over LME Cooling October contract $46.94 below LME three-month, November $38.99 above, 29 September Gap largely closed
Yangshan premium $118 a tonne $119 a tonne, early October Flat
Has the copper backwardation narrowed since the 12 October piece?
Yes. The LME cash premium over three-month copper was $64 a tonne on 5 October, according to Permutable's copper inventory analysis, against $248 in our 12 October piece and a $545 peak in August. Prompt metal still costs more than forward metal, but being short prompt is cheaper to hold than it was.
The narrowing followed the August deliveries. More than 20,000 tonnes went on warrant in one day and the spread fell from $545 to $248 as reported by Oilprice. Permutable has LME stock recovering from about 205,000 tonnes in mid-August to 244,900 tonnes on 5 October.
The curve has not gone flat. The International Copper Association Australia weekly brief says the LME prompt spread widened to a monthly high in late September as Chinese smelters scheduled Q4 maintenance, without giving a level. SMM still described LME copper as in backwardation on 29 September. The two publishers time-stamp differently, so compare the direction and not the last dollar.
Is the cancelled share of LME copper still near half?
Reported cancelled warrants are still near half of LME copper stock, but the outlet carrying that figure labels it unconfirmed. Stock itself was 244,900 tonnes on 5 October against 240,250 tonnes in our 12 October piece, so the headline has barely moved and the available share has not visibly improved.
Cochilco's figures, as reported by Discovery Alert, show LME stock down 3,750 tonnes in one session to 244,900 tonnes. The same article puts available copper near 133,725 tonnes and marks both that and the cancelled share unconfirmed.
Those two figures do not agree with each other. 244,900 tonnes less 133,725 tonnes leaves 111,175 tonnes cancelled, about 45% and not half. Until the LME warrant report by location settles it, carry the cancelled share as roughly 45% to 50%.
What returns cancelled metal to the board is price. On 19 August, with the backwardation near $550, Benchmark reported on-warrant stock up 63,000 tonnes in three days, with a significant amount of cancelled stock re-warranted. At $64, does the spread still pay anyone to bring cancelled metal back?
Is the COMEX premium over LME copper still open?
Barely. On 29 September SMM had the October COMEX contract at a $46.94 a tonne discount to LME three-month copper and the November contract at a $38.99 premium, neither enough to cover freight, financing, storage and delivery. At end-July the gap was about $420 a tonne, according to the ICA Australia brief.
The White House's 28 September window for a refined copper decision passed with no announcement. SMM cautions that silence does not confirm the tariff is dropped: a 15% tariff in 2027, rising to 30% in 2028, was previously considered and has not been ruled out.
COMEX warehouses held 706,818 tonnes on 2 October, per the Cochilco figures above. SMM expects metal already in the US to be slow to return, given financing, handling and re-export costs. One unconfirmed snapshot put the COMEX premium near 0.6% around 2 October. SMM's October and November figures carry opposite signs, so a single percentage is thin evidence.
Is China still paying up for copper?
Broadly yes. The Yangshan premium was $118 a tonne in the Finimize report behind our 12 October piece and $119 in early October, per Business Recorder, so it has held at that level. SMM put its domestic #1 cathode premium near $205 a tonne on 29 September, the highest since October 2023.
SMM ties that premium to the same flow as the COMEX one. Metal pulled toward the US left less cathode for Asia, and SMM-tracked Chinese social inventories sat at a multi-year low of 78,300 tonnes. SHFE stock was frozen at 38,744 tonnes through the holiday, so the Shanghai picture is incomplete until the refreshed reading lands.
Two readings of the same update
Reading one: the squeeze is easing. The spread is $64, LME stock is up from about 205,000 tonnes in mid-August, and the COMEX arbitrage is shut. Under this reading cover can lengthen, with staggered forwards.
Reading two: the pressure has moved rather than gone. About 700,000 tonnes sit in US warehouses, Chinese inventories are low, the cancelled share is near half, the prompt spread hit a monthly high in late September and the tariff has not been ruled out. Under this reading, hold the tenor short.
Both readings use the same figures. They differ on where the cancelled metal and the US stock go next. If cancelled metal leaves and the COMEX gap reopens in the same month, is your hedge tenor still matched to your quotation period?
What is still unresolved
Whether cancelled metal returns. Only the LME warrant report by location will show it, and the incentive is weaker at $64 than at $545.
Whether the COMEX gap reopens. It turns on a tariff decision. Morgan Stanley flags an explicit rule-out as the key downside risk, which could release US stocks back into a tight ex-US market.
Whether Chinese restocking meets low inventories. The post-holiday SHFE reading is the first check.
Square the three against the next warrant report and the curve stays a cost you manage. Novaex carries the same lines on screen: LME and MCX live, with COMEX and SHFE computed into the cross-exchange arbitrage view. Every source above is linked so you can check the working.