Nickel stocks at records vs Indonesia quota cut: which sets hedge cover?
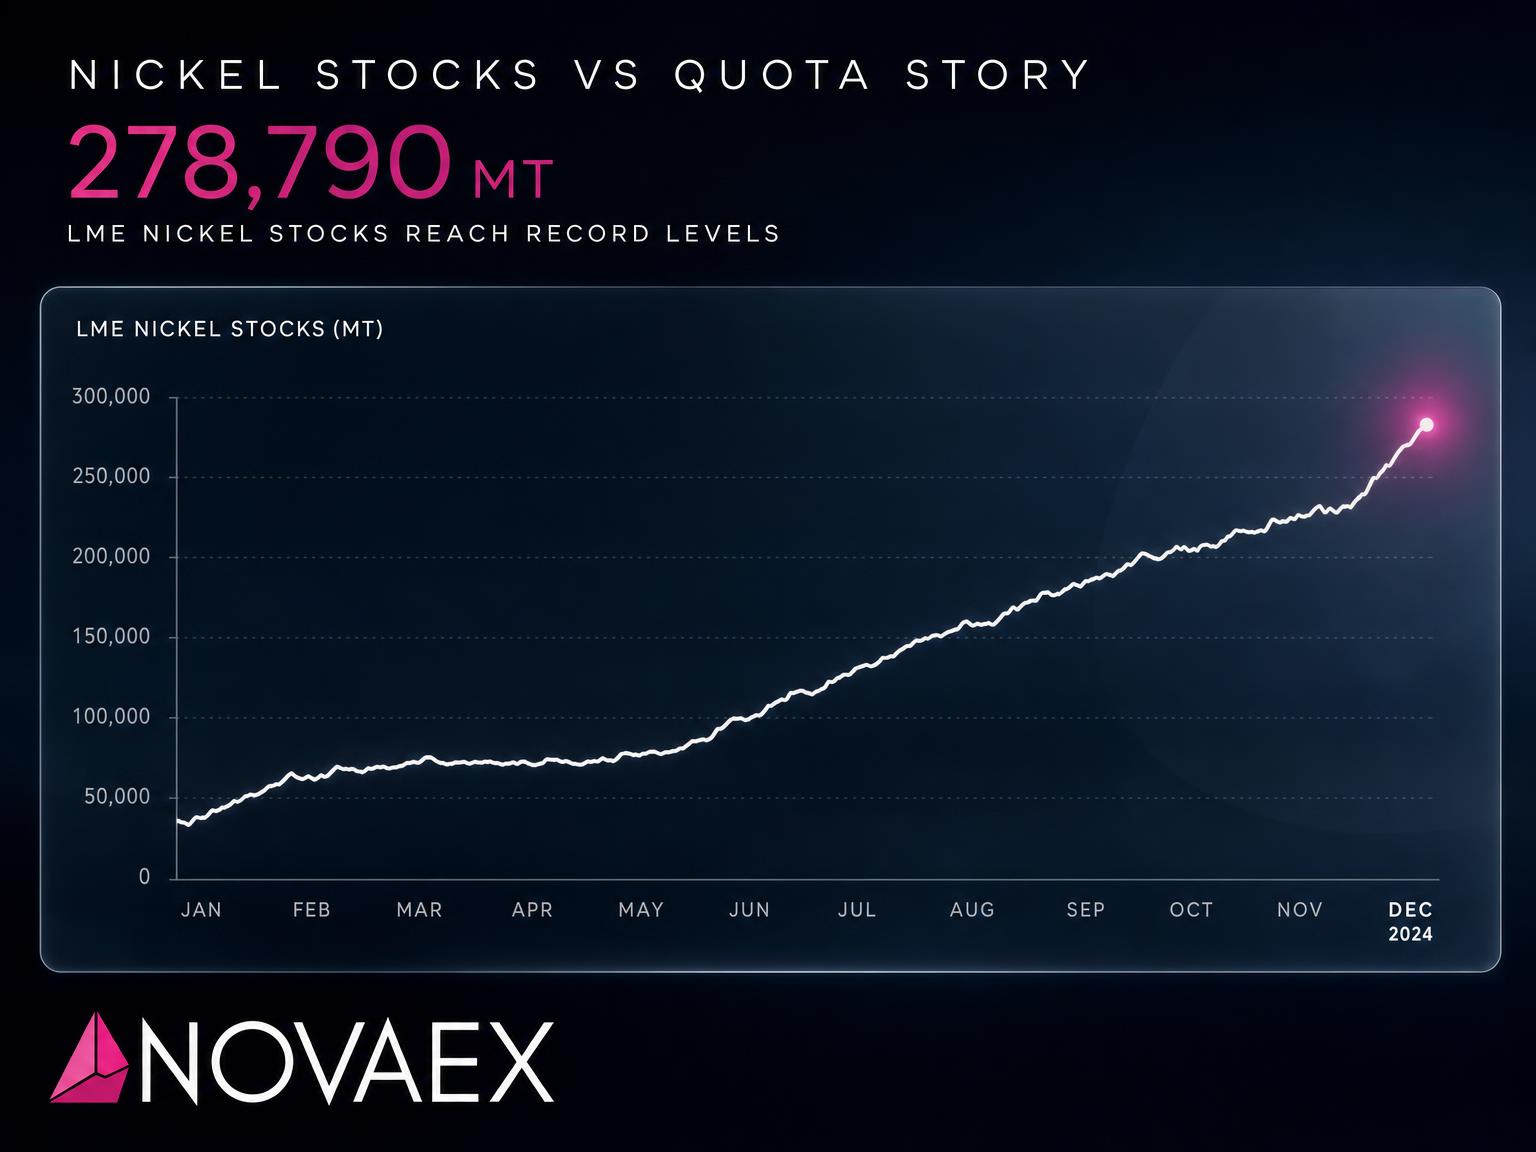
LME nickel sits near 279,000 t while Indonesia cuts 2026 ore quota by nearly a third. Two readings, one hedge decision.
Nickel, October quotation period. LME stocks sit near 279,000 t and Indonesia has cut next year's ore quota by almost a third. One says cover less. The other says do not. The desk that squares those two readings before setting cover keeps margin. The desk that picks one on instinct finds out at month-end.
Record stocks have not removed quota risk, and a lower quota has not removed the metal already on warrant. LME nickel stood at 278,790 t on 17 September. That is deliverable Class 1 metal the short can actually get. Indonesia's 2026 ore quota sits at 260 to 270 million wet metric tonnes, against 379 million approved for 2025. That is ore in the ground, not cathode in a shed. Hedge policy right now has to price both.
How high are LME nickel stocks right now?
LME nickel stocks stood at 278,790 t on 17 September, after building for two years to the highest level in more than four years. Corroborating mid-September reads sit in the same zone, around 274,000 to 278,500 t. The direction is not in doubt. Surplus Class 1 keeps arriving at the warehouse.
The headline understates the pile. LME registered plus off-warrant nickel rose 57.6% through 2025 to 367,310 t, the largest increase of any core LME metal, in a Reuters review of LME shadow stocks. Combined LME and Shanghai exchange stocks touched a record 468,600 t around mid-2026, about six weeks of global use, in a record of the combined stock overhang. ING's read matches: the Class 1 surplus keeps getting refined and absorbed by the LME, in its nickel surplus analysis.
One January day showed what that overhang does to a rally. A single 20,760 t warranting, the largest since December 2019, cut LME three-month nickel from a 19-month high near $18,800 to $17,895 the same day. Metal on warrant caps price.
What did Indonesia actually cut?
Indonesia cut the 2026 nickel ore RKAB quota to 260 to 270 million wet metric tonnes, against 379 million approved for 2025. That is 109 to 119 million tonnes lower, or 29 to 31% down, reported by Argus on the 2026 quota and Benchmark on the lower RKAB.
Ore quota is not cathode supply. Indonesia mines around 60% of world nickel, mostly into nickel pig iron and growing high-pressure acid leach output for batteries. A lower ore number tightens feed to smelters over months. It does not pull a single tonne out of an LME shed this week.
Enforcement is the swing factor. Jakarta has seized part of Weda Bay, suspended permits, moved RKAB to annual approval, and halted new permits for plants making only intermediate products. ING flags Indonesian policy as the main upside risk to price. The quota is a brake on future units. Stocks are units already built.
Why doesn't record metal settle it?
Because the two numbers measure different things.
Stocks measure deliverable cover today. Only Class 1, about a quarter of primary supply, can deliver onto the LME. That is exactly what is piling up: Chinese and Indonesian cathode flowing into LME sheds, with Chinese-origin share of available tonnage reaching 70% in October last year. For a short quotation period, that is the only number that matters.
Quota measures ore available to become metal later. Lower 2026 ore approvals bite in NPI output, in HPAL feed, in next year's cathode units. Slowly, then all at once if smelters run short.
Cancelled warrants sit between the two. Recent SMM data put cancelled nickel warrants near 42,228 t, over half of registered stocks, in its cancelled-warrant read. Cancelled means earmarked to leave. High cancels against high stocks means metal is both arriving and queuing to go. That ratio moves before price does.
Surplus arithmetic backs the caution. The market ran a 209,000 t surplus in 2025 with 261,000 t forecast for 2026. Stainless demand, over 60% of use, stays soft. Battery demand grows but leaks to lithium iron phosphate chemistries. ING sees nickel averaging $15,250/t in 2026, range-bound, capped by stocks, floored only by disruption risk.
Which reading should set hedge cover?
Neither, on its own. Set cover off the tension between them.
Reading What it says What to check before the desk opens
Deliverable metal Stocks near 279,000 t plus off-warrant shadow cover near-term shorts. Rallies get sold into warranting. Live and cancelled warrants, origin mix, weekly LME stock change
Quota risk 2026 ore approvals down by nearly a third. Forward units tighten if enforcement holds. RKAB approvals issued vs quota, smelter feed reports, Weda Bay restart news
Demand Stainless soft, batteries shifting to non-nickel chemistries. Surplus persists. Stainless order books, NMC vs LFP share, quotation-period spreads
Practical line: hold forward cover against priced sales, do not pre-sell length into a quota headline while warrant stocks can still deliver against you. A sale with a fixed quotation period gets hedged in that period. Unpriced ore exposure stays open until the quota path firms. Square physical, hedge and broker books line by line each morning. The gap between them is where this market charges tuition.
Two readings, one book. Stocks say the metal is here. Quota says the next metal may not be. Worth checking the trail before the window moves.